What Energy Storage Buyers Need to Know Heading Into 2027
Key facts
- Large loads like data centers now contract directly with construction firms to build storage systems, bypassing traditional developers entirely
- Some construction firms entering the energy storage market have never built a battery system before, creating significant execution risks for buyers
- Buyers must fund quality assurance as a defined budget line item to manage shifting standards in cell technology and sourcing rules
- Projects specifying battery models that have not yet cleared regulatory authorization require a backup plan to prevent shipment stalls
For most of the past decade, energy storage developers have handled battery procurement themselves, building that expertise in-house, project after project. That is no longer the only path into the market. Large loads, including data centers and other big electricity users, now contract directly with construction firms to build storage systems themselves, bypassing developers entirely, and some of those construction firms have never built one before.
Those buyers face a choice: hire developers who already have the expertise, or build that expertise in-house under real time pressure. Either path carries the same exposure if buyers skip the fundamentals below. This shift poses the biggest risk facing storage buyers heading into 2027.
Quality assurance, cell technology, sourcing rules, tariffs and financing standards are all shifting at once, often within the same procurement cycle. Buyers who succeed next year will fund quality assurance as a defined budget line item.
Quality Assurance Cannot Stop at the Cell
Cell and module manufacturing has matured, and automation keeps defect rates low—but not zero—at that stage. System integration has not kept pace. Wiring, thermal management and fire suppression still depend heavily on manual assembly. That dependency concentrates problems in exactly those areas.
“System-level” also extends further than the container itself. It covers the network architecture tying a system together, the design of backup power for that network and how the system integrates its uninterruptible power supply. A factory audit limited to cell quality assurance never touches any of that.
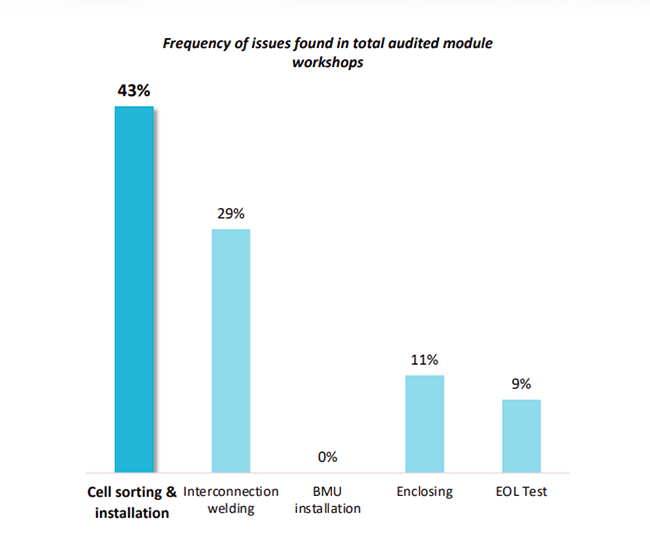
1. Cell sorting and installation accounted for 43% of defects found in audited module workshops, more than the next three categories combined. Source: Intertek CEA
2. Fire suppression system defects led all system-level findings at 8.2% of inspected units, followed by appearance defects at 5.8% and water ingress issues at 4.4%. Source: Intertek CEA
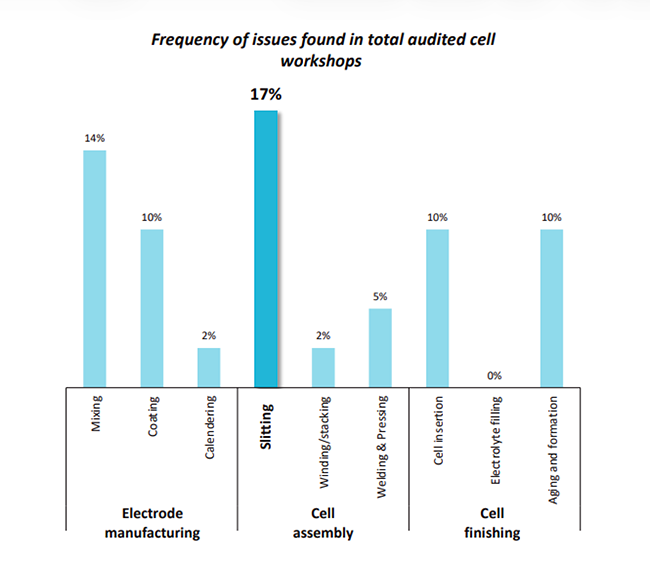
3. Slitting produced the highest defect rate among audited cell manufacturing steps, at 17%, followed by mixing at 14%. Source: Intertek CEA
Intertek CEA’s factory audits (Figures 1, 2, and 3) back this up. System-level defects (Figure 4) accounted for 75% of quality findings across our 2025 inspections, compared with 15% at the cell level and 10% at the module level. Within system-level findings, 47% involved balance-of-system issues such as coolant leaks or malfunctioning alarms. Another 42% involved enclosure problems like water ingress, and 11% involved failed performance tests.
A buyer who audits only the cell supplier checks the part of the system least likely to fail.
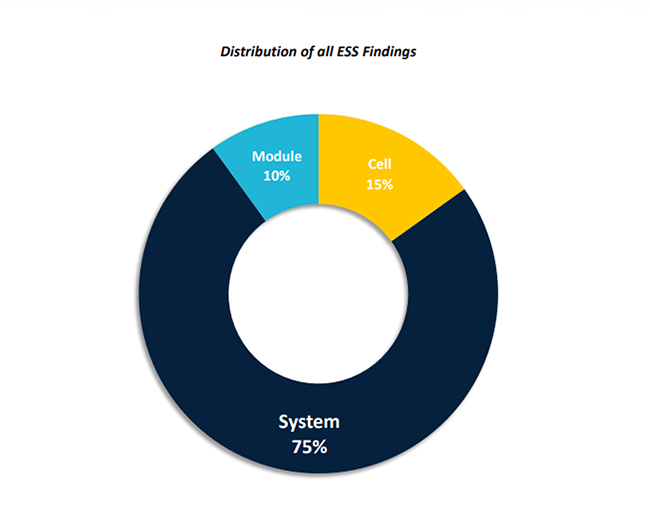
4. System-level defects accounted for 75% of quality findings across Intertek CEA’s 2025 factory audits, compared with 15% at the cell level and 10% at the module level. Source: Intertek CEA
Bigger Cells Carry Thinner Track Records
That industry-wide track record took years to build. Cell formats keep growing, and the newest, largest cells have not had the same runway to earn it. A few years ago, 280 amp-hour cells set the standard. Then came 314 amp-hour cells. Manufacturers now ship cells rated at 500 amp-hours and beyond, with some exceeding 1,300.
Larger cells need fewer connections, fewer weld points and less material. That appeal makes sense, but a bigger cell does not automatically perform better. A cell’s manufacturing maturity, R&D investment and third-party testing history matter more than its rated capacity. Buyers should ask how long a cell design has stayed in production and whether independent testing backs the manufacturer’s claims.
Responsibility for thermal performance splits between two parties, and buyers should know which owns which piece. The cell manufacturer supplies the heat-load data the cell generates. The system integrator then designs the cooling system around that data, whether that means a larger cooling unit, cooling built into the module itself, or some combination.
If the heat-load data is wrong—because of a mistake by the OEM or a miscommunication about how the battery will be used—the integrator will design an undersized cooling system. That gap typically will not surface until the system operates in the field. A separate risk exists even when the heat-load data is accurate: using the battery beyond its approved use case can overheat it, because the cooling system was sized only for that narrower, approved operating envelope.
This shift also complicates projects built in phases if a different cell is used in later phases. Battery racks with different cell sizes balance differently. Mixing cell formats across a phased expansion can strain a system’s battery management and asset-tracking practices. Buyers augmenting existing systems need this built into the design from the start, not discovered or retrofitted afterward.
Supply Chain Diversification Now Carries a Compliance Requirement
Cell technology is one axis of risk. Where that cell comes from is another. Tariffs are pushing manufacturing away from single-country concentration, and that diversification now affects tax credit eligibility as well as sourcing strategy.
Section 48E investment tax credit rules require a minimum share of a storage project’s cost to trace to non-prohibited-foreign-entity sources. That threshold sits at 55% for projects beginning construction in 2026 and rises five percentage points annually, reaching 75% by 2030. Falling short of that threshold disqualifies the credit outright.
Full bill-of-materials traceability, down to sub-tier components, no longer counts as a nice-to-have. The compliance test requires it. Buyers should also build backup suppliers into procurement contracts before a primary source falls out of compliance, rather than after.
Regulators Have Frozen New Inverter Authorizations
Buyers relying on foreign-produced power inverters face a related problem. Regulators froze new equipment authorizations for foreign-produced power inverters with remote communication capability starting in late July, then narrowed the scope in August to utility-interactive inverters specifically, while exempting inverters that qualify for the Section 45X domestic manufacturing tax credit. That freeze still covers storage inverters as well as solar.
Previously authorized models remain unaffected, but any project specifying a model that has not yet cleared authorization needs a contingency. The same discipline that protects against losing a cell supplier’s compliance status applies here: line up a backup before a project needs one, not after a shipment stalls.
Bankability No Longer Belongs to the Developer
Equipment risk is not the only thing changing. The question of who can vouch for a project is changing too. Bankability historically relied heavily on the developer’s own assessment. That reliance will no longer be sufficient, echoing a familiar pattern already seen in solar.
Solar lenders once leaned more on developer assurances and insurance coverage to manage equipment risk. As claims accumulated, lenders shifted toward requiring independent verification instead. Storage financing is following the same arc, only faster.
Banks and lenders increasingly want independent verification of a system’s quality and performance rather than a vendor’s word for it, and that verification takes a specific form in practice. Lenders now ask firms such as Intertek CEA to review bankability reports after the fact, because most bankability reports do not thoroughly cover manufacturing quality assurance.
That gap matters: a bankability report can describe a supplier favorably without ever seeing the underlying factory data, even if a third-party auditor has already collected it. A strong track record in the industry no longer serves as sufficient proof on its own. Buyers should expect lenders to ask for evidence, not assurances.
Put a Budget Behind the Plan
None of the above matters without funding. Cell validation, thermal design review, tariff and compliance documentation, backup supplier contracts, factory quality assurance and independent bankability verification all cost something real. A quality plan that sits in a drawer protects nobody.
Contract reviews, factory audits, factory acceptance testing, a witnessed commissioning and a witnessed site acceptance test all cost money too. That cost belongs in the project budget, not on a list of optional add-ons.
Set aside real dollars per kilowatt-hour for this work before construction starts. That might mean 25 cents per kilowatt-hour, or 50 cents, depending on the project, but it means an actual figure attached to an actual budget line, covering supply chain and compliance documentation, third-party contract review, factory quality assurance and a witnessed commissioning and site acceptance test.
A plan without a budget behind it amounts to nothing more than a document. Heading into 2027, the buyers who protect their projects will fund the full scope of diligence, from cell and supply chain validation through commissioning, rather than treating any piece of it as optional.
—Jeff Zwijack is associate director, Energy Storage, at Intertek CEA , where he advises utilities, developers and policymakers on storage deployment, market participation and regulatory compliance.
Few moments have placed more pressure on the U.S. power sector than the one we’re in now—surging load growth, an evolving generation mix, mounting reliability concerns, rising costs, and a regulatory environment in flux. But those pressures look very different depending on where you sit on the grid.
In this session, executives from several of the industry’s most influential associations share what’s at the top of their members’ agendas, the challenges keeping their members up at night, and the work their organizations are doing to help meet those challenges head-on.
Attendees will leave with a clearer picture of how different segments of the power sector are approaching today’s defining issues, and where their priorities align, diverge, and intersect.
This executive panel brings together leaders from across the power sector for an in-depth discussion of the issues shaping the industry today. The discussion may explore current trends in generation, transmission, and distribution, along with the regulatory environment, supply chain pressures, demand growth, and workforce considerations influencing strategic decisions. The session will offer attendees a direct view into how utilities are adapting their planning, operations, and investment priorities to meet a rapidly evolving landscape.
Women are driving innovation and transformation across the power sector. This panel highlights how diverse leadership strengthens organizational resilience, fosters inclusive practices, and fuels progress in a rapidly evolving industry. Hear from trailblazers as they share strategies for recruiting women into energy roles, advancing careers, and breaking barriers. Whether you're new to the field or a seasoned professional, this session offers insights to empower your journey and build a more inclusive energy future.
Across the country, state policymakers and regulators are taking proactive steps to meet the challenge of load growth. What are the policies, regulatory strategies, and state programs that have worked for responding to growth while keeping costs low for ratepayers?
The U.S power sector is going through profound change. The new administration slowed the pace of regulatory initiatives, courts placed key rules on hold, and multiple environmental standards affecting generation and transmission entered periods of reconsideration. At the same time, demand pressures from data centers, electrification, and broader economic growth continued to mount, leaving utilities and power producers facing critical choices about where to invest in new generation, how quickly to retire aging assets, and how to plan for compliance in a policy environment defined by uncertainty.
Against this backdrop, the session will provide a comprehensive update on the environmental regulations shaping the industry and examine how ongoing litigation could alter the trajectory of rulemaking and permitting timelines into 2026 and beyond. It will also challenge the traditional view of permitting as a purely technical and regulatory exercise governed by statutes, studies, and agency schedules. In practice, permitting is deeply political: community sentiment, local leadership dynamics and organized advocacy cam all determine whether a project advances smoothly or becomes mired in controversy. Building on this dual regulatory and political context, attendees will learn practical approaches for treating permitting as both a compliance requirement and a political pathway.
This panel will focus on AI’s role and application across the utility lifecycle. From generation, control systems, and emission monitoring, AI is playing an ever increasingly important role on security and predictive maintenance.
Pvola take
Developers must differentiate their value proposition by emphasizing proven system integration expertise, as large industrial buyers increasingly attempt to self-build storage projects. The primary risk for investors is not just equipment cost, but the operational failure of inexperienced construction firms handling complex thermal and wiring integration. Success in 2027 depends on treating quality assurance as a non-negotiable budget item rather than an optional add-on, ensuring that system-level defects do not undermine the project's bankability or long-term performance.
Frequently asked questions
Why is direct contracting by data centers a major risk for storage buyers in 2027?
Construction firms often lack prior experience building storage systems, creating exposure if buyers skip fundamental checks. This shift bypasses developers who previously held the necessary procurement and integration expertise.
What specific budget line item must storage buyers fund to mitigate integration risks?
Buyers must fund quality assurance as a defined budget line item. System integration has not kept pace with cell manufacturing, leaving risks in wiring and thermal management.
How does the shift in bankability affect the role of developers in storage projects?
Bankability no longer belongs solely to the developer, as equipment risk and financing standards are changing. Buyers must manage these risks directly when contracting with construction firms.